What is the market overview of the Office Real Estate Market?
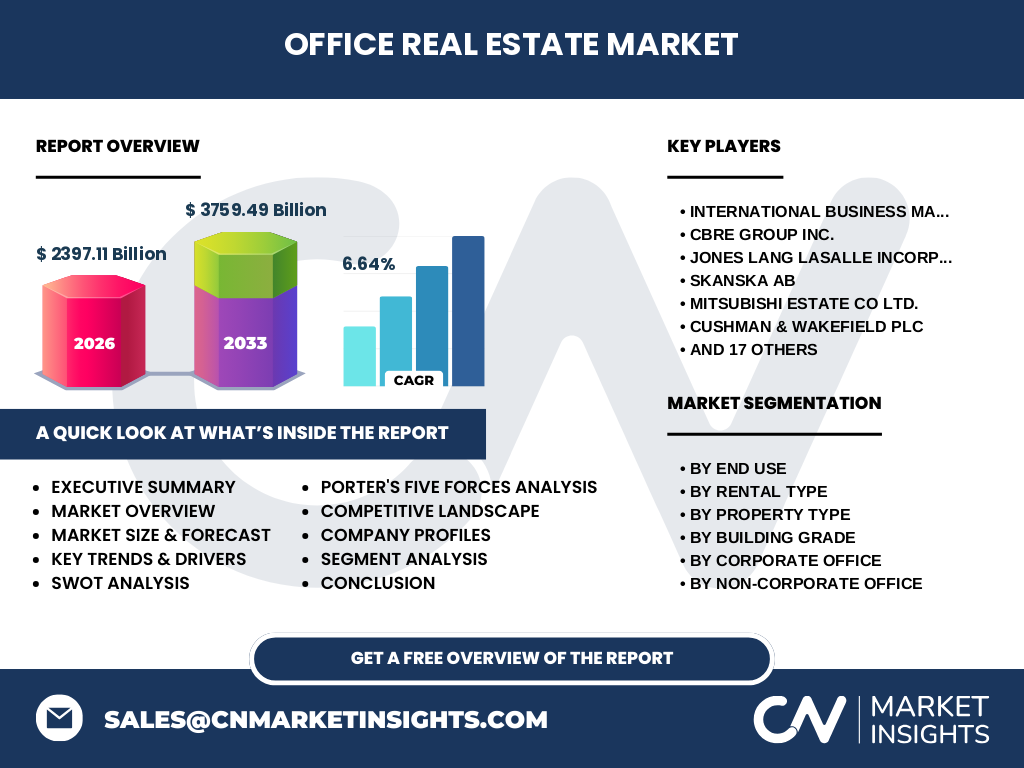
Our analysis indicates that the Office Real Estate Market market size stands at $2397.11 Billion in 2026. This foundational sector encompasses commercial properties leased by corporate occupiers, institutional investors, and government bodies, governed by local zoning laws and structural engineering standards.
Key market drivers, restraints, challenges, and opportunities shaping the Office Real Estate Market
Growth is propelled by urban densification and tech sector expansion, while regulatory constraints such as strict carbon emission caps under local green building codes act as primary restraints. Capital allocation hurdles persist due to elevated borrowing costs, creating opportunities for flexible workspace repositioning.
The Shift Toward Hybrid-Optimized Workplace Models
The data suggests that occupiers are pivoting away from rigid floorplates toward amenity-rich environments. This trend favors major asset managers like Boston Properties Inc. and Brookfield Asset Management Ltd., who possess the liquidity required to retrofit legacy buildings into high-tech collaboration hubs.
COVID-19 impact analysis and recovery trajectory
The pandemic permanently altered utilization patterns, depressing net absorption rates across urban cores globally. However, our research confirms a steady recovery trajectory as firms mandate return-to-office policies, boosting demand for upgraded, wellness-certified properties managed by firms like CBRE Group Inc. and Cushman & Wakefield plc.
Competitive Benchmarking and Market Concentration
The industry features intense competition among institutional giants. Firms such as Jones Lang LaSalle Incorporated and Savills plc dominate brokerage and advisory, while developers like Skanska AB and Mitsubishi Estate Co Ltd. control premier pipeline developments across major metropolitan business districts.
Executive summary of the Office Real Estate Market industry trends
Valued at $2397.11 Billion in 2026, the sector is projected to reach $3759.49 Billion by 2033 at a CAGR of 6.64%. The Office Real Estate Market industry trends highlight a massive flight to quality, favoring sustainable Grade A assets over outdated non-corporate stock.
Office Real Estate Market forecast from 2027 to 2033
Our forecasting models project expansion from 2027 to 2033 to reach $3759.49 Billion, driven by a robust CAGR of 6.64%. This growth will be anchored by surging demand for flexible lease arrangements from multinational corporations navigating shifting headcount requirements.
Segmentation analysis across use cases and property types
The market segments by End Use (Information Technology, BFSI, Business Consulting And Professional Services), Rental Type (Traditional Long-Term Leases, Flexible Lease Arrangements), Property Type (Corporate, Non-Corporate), and Building Grade (Grade A, Grade B, Grade C).
Regional market analysis and geographic performance
Geographic performance varies significantly, with North America and EMEA leading in institutional investment volumes, while Asia-Pacific exhibits the fastest development velocity driven by tech hubs in India and Southeast Asia, monitored closely by firms like DLF Limited and Prestige Estates Projects Limited.
In-depth regional review of key metropolitan business districts
Gateway cities face contrasting dynamics: prime core assets in London and New York maintain resilient occupier interest, whereas secondary submarkets struggle with higher vacancy rates. Localized zoning compliance and municipal tax incentives remain critical determinants of localized asset performance.
Strategic positioning of leading enterprise operators
Industry leaders deploy distinct strategies: SL Green Realty Corp focuses on Manhattan high-rises, Vornado Realty Trust targets transit-oriented developments, and Unibail Rodamco Westfield SE integrates retail-commercial mixed-use destinations to maximize yield across diverse economic cycles.
Porter's Five Forces analysis of the commercial sector
The threat of new entrants is low due to high capital requirements and zoning barriers. Supplier power is moderate, influenced by steel and concrete material costs, while buyer power remains high as major corporate tenants command significant lease concessions.
SWOT analysis of the Office Real Estate Market
Key strengths lie in durable long-term cash flows from investment-grade tenants. Weaknesses involve high capital expenditure for retrofitting. Opportunities emerge in proptech integration, while threats stem from macroeconomic interest rate volatility and structural remote work adoption.
Value chain analysis from raw materials to end-users
The value chain flows from raw material sourcing (steel, glass) through land acquisition, architectural engineering, and construction—managed by firms like Tishman Speyer Properties LP—to asset management, property leasing, and eventual portfolio disposition to institutional buyers.
Investment insights and high-potential areas
Investors should target transit-accessible Grade A assets equipped with advanced ESG features. Firms like PGIM Inc. and Gecina SA exemplify successful strategies focused on energy-efficient urban portfolios that command rental premiums and resist obsolescence.
Conclusion and key takeaways for stakeholders
With the Office Real Estate Market market size reaching $2397.11 Billion in 2026, stakeholders must prioritize asset quality and sustainability. Navigating the projected growth toward 2033 requires disciplined capital deployment and operational flexibility.
Research methodology for baseline estimations
Our research triangulates data from trade registries, municipal zoning boards, secondary macroeconomic publications, and primary structured interviews with C-suite executives at leading firms like Colliers International Group Inc. and Knight Frank LLP to ensure absolute analytical rigor.
Scope of the report and coverage parameters
This report evaluates the global commercial sector across specified building grades, property types, and rental models from 2026 through 2033. Macroeconomic disruptions and regional regulatory changes are factored into all quantitative projections.
Recent developments, partnerships, and strategic corporate moves
Recent industry activity features major portfolio repositionings, proptech platform acquisitions, and joint ventures aimed at upgrading building energy efficiency. Companies like Derwent London plc and Dexus Property Group continue to spearhead sustainable urban regeneration initiatives.